

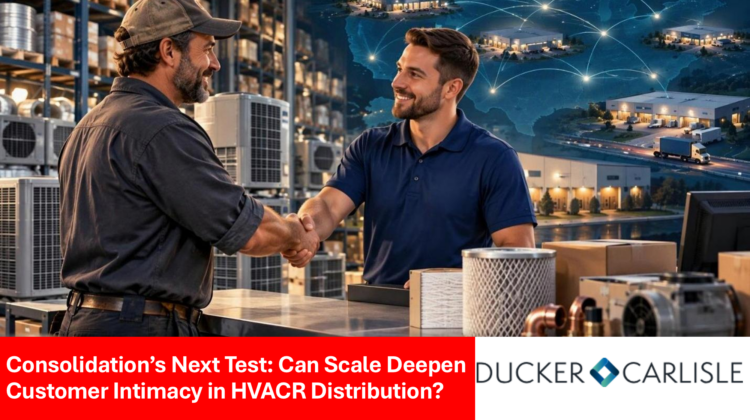
TL;DR: The 2026 HVACR distribution deals show buyers paying for local trust, not branch counts. Scale creates lasting value only when it helps the branch serve contractors better, so acquirers should centralize the back office and keep customer decisions local.
The first article in this series, HVAC Distributors – Before You Sell, Ask Two Questions?, made a simple argument: independent distributors have endured despite powerful economic arguments for consolidation because they possess an advantage that is difficult to replicate: customer intimacy. They know their contractors, markets, jobsite realities, and supplier ecosystems. They can act quickly and flexibly when a customer needs an exception, an expedited delivery, technical help, or an unconventional solution.
The most recent wave of HVACR distribution acquisitions does not undermine that premise. Instead, it clarifies the real strategic question facing acquirers and independents alike: Can greater scale enhance customer intimacy, or will it diminish it?
Recent transactions suggest the most sophisticated consolidators know what is at stake. Consider:
- Watsco’s acquisitions of Jackson Supply Company and The Granite Group
- Home Depot subsidiary SRS Distribution’s completed purchase of Mingledorff’s and pending acquisition of Lohmiller & Company
- Hajoca’s acquisition of American Refrigeration Supplies (ARS); and
- the growth of acquisition platforms such as Advantage Distribution Holdings (ADH)
all point to a common investment thesis. Buyers are not simply purchasing branches, revenue, or inventory. They are acquiring local market relevance, contractor trust, OEM relationships, and operating capabilities. Then they attempt to add scale without destroying those assets.
Buyers Are Paying for More Than Distribution Volume
At a surface level, the logic of these transactions appears conventional. HVACR distribution is fragmented. Larger companies have greater purchasing power, more resources for logistics and inventory optimization, and the capital to invest in technology, digital commerce, delivery fleets, training, and branch networks.
The best targets in recent transactions are not generic wholesalers. They are entrenched local businesses with long-standing contractor relationships, local technical knowledge, experienced employees, and valuable OEM affiliations. For example,
- Watsco described Jackson Supply as one of the largest HVAC distributors in the Sunbelt, serving approximately 5,000 customers from 25 locations with Goodman and Amana equipment plus parts and supplies from roughly 200 vendors.
- SRS acquired Mingledorff’s, a 42-location distributor serving residential and commercial customers across five Southeastern states,
- Lohmiller, a Denver-based Carrier distributor with four Colorado locations, brings long-standing OEM and contractor relationships.
In each case, the local business is valuable precisely because it has already won the right to serve its market. The acquisition thesis begins with preserving that right.
Recurring Revenue and Share of Wallet Are Central
The most compelling distributor platforms also recognize that HVACR is more than an equipment business. Equipment sales matter, but parts, supplies, controls, refrigerants, accessories, plumbing, hydronics, and refrigeration products provide a more recurring and often less cyclical revenue base.
This is why recent acquisitions frequently cross category lines.
- Watsco’s Granite transaction adds a diversified plumbing and HVAC distributor with 82 Northeast locations.
- Hajoca, long known for plumbing, added ARS and its 34 branches serving HVAC and refrigeration contractors across seven Southwestern states.
- SRS is broadening its offering for professional contractors by adding HVAC equipment, parts, and supplies at scale.
These buyers are building broader platforms that can capture a larger share of each contractor customer’s purchasing activity.
The winning distributor is not merely the lowest-cost source of a piece of equipment. It increasingly becomes a productivity partner that helps the customer source materials, manage inventory, coordinate delivery, find technical answers, and reduce time lost in the field. Scale can deepen customer intimacy when it lets the local branch solve more of the contractor’s problems in one place.
Preserve What Made the Target Valuable
The strongest evidence of the prevailing investment thesis may be what acquirers repeatedly promise to preserve: leadership continuity, local brands, local relationships, and operating autonomy. Jackson Supply and The Granite Group both continue under their existing management teams inside Watsco. SRS said Lohmiller’s owners will continue to lead the business. Hajoca is keeping the ARS name and leadership, and ADH committed to preserving Badger Metals’ “local leadership, brand, and customer-first culture.”
That is not merely transaction messaging. It reflects a practical reality. An acquirer can centralize financial controls, procurement analytics, digital tools, and logistics planning. But it cannot easily centralize trust.
What to Centralize and What to Keep Local
For acquirers, the integration plan is where the investment thesis succeeds or fails. Finance, purchasing analytics, IT, and fleet and logistics planning usually benefit from scale. The decisions contractors feel every day belong at the branch: credit and pricing exceptions, local inventory mix, counter and technical staffing, and the outside sales relationship. When headquarters takes over those decisions, contractors notice the change before the income statement does.
The Strategic Standard for Future Deals
The consolidation wave will continue because the underlying logic is compelling: a fragmented industry, attractive recurring demand, meaningful scale benefits, and substantial opportunity to improve contractor productivity. Yet the long-term winners will not be the buyers that simply accumulate the most branches. They will be the ones that use scale to make local distributors better at what made them successful in the first place.
For independent distributors evaluating their future, the question remains the same as in Part One: Who are we, and why are we here? If the answer is rooted in customer intimacy, owners should judge any offer by a demanding standard: Will this buyer provide the capital, technology, inventory depth, adjacent product breadth, and operational support to enhance that intimacy? Or will it impose standardization that weakens it? The three buyer questions in Part One offer a practical way to test the answer. Consolidation can be a powerful catalyst for growth. But in HVACR distribution, scale creates lasting value only when it amplifies the local relationships at the heart of the business rather than replacing them.
About the Author
Kevin Sarb is a Principal at Ducker Carlisle, where he leads the Industrials Practice with a focus on energy, climate technologies, and commercial excellence. He brings 20 years of management consulting experience helping industrial clients develop growth strategies and build commercial capabilities.
Contact: ksarb@duckercarlisle.com | duckercarlisle.com


Leave a Reply Cancel reply